Business Loans in Minnesota - Get Funded Fast

Apply now! It’s quick, easy and free.
Free Consultation – No Obligation

No Cost, No Obligation Quote

    Current monthly sales deposit average to your business bank account?

    How much Working Capital would you like for your business?

    By providing your phone number and submitting this form, you consent to receive text messages from United Capital Source about your financing inquiry. Message frequency may vary. Message and Data Rates may apply. Reply STOP to opt out of further messaging and HELP for assistance or call 646-448-1700. View our Privacy Policy and Terms.

    Business loan approval process with clock and dollar sign icons.

    Apply In Minutes

    Use our easy online form to apply & get fast approvals
    Business loan consultation image for United Capital Source, highlighting financial solutions and exp.

    Compare Options

    Secured & unsecured options, some with no personal guarantee
    Business loan approval process at United Capital Source with expert guidance.

    Customize

    Pick the terms that work best for your business
    Step 4 icon of a hand receiving a dollar coin, marking the funding stage of the factoring application

    Get Funded

    Funds in a few business days for most programs

    Here’s what business owners like you are saying:

    What our clients are saying:

    Business Loans in Minnesota - Get the Funding You Need

    Key Takeaways:

    • 💰 Diverse Loan Options: Minnesota businesses can access term loans, SBA-guaranteed loans, business lines of credit, equipment financing, and merchant cash advances.
    • 📈 Growth & Expansion: Business loans help fund working capital, inventory, hiring, marketing, and expansion efforts.
    • ⚡ Fast Online Funding: Alternative lenders offer quick approvals and funding, ideal for businesses needing immediate cash flow.
    • 🔍 Credit & Collateral Considerations: Loan eligibility depends on credit score, revenue, time in business, and in some cases, collateral.
    • 📜 State & Local Programs: Minnesota offers additional funding through state-backed initiatives and grants for small businesses.
    • ⚠️ Risks & Costs: Interest rates, fees, and repayment terms vary—businesses should compare lenders to find the best fit.
    • 💼 Strategic Use of Financial Resources: Effectively utilizing financial resources obtained through loans can foster business growth and sustainability, covering areas such as cash flow management, business expansion, and equipment purchases.

    Minnesota’s diverse economy largely reflects the US economy. This provides ample opportunity for small businesses, drawing many entrepreneurs to the Land of 10,000 Lakes. However, many entrepreneurs require financial help to thrive in a competitive state.
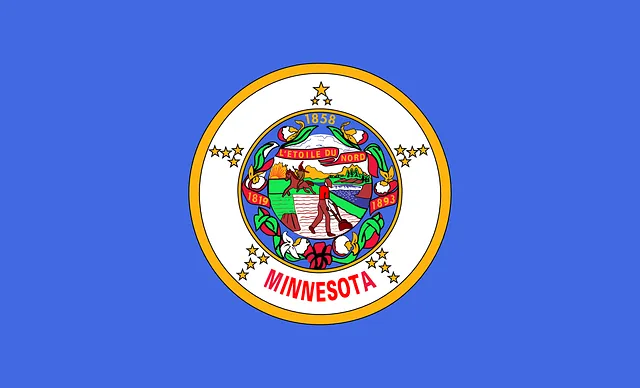
    Minnesota state flag with the state seal, stars and the motto L'Etoile du Nord on blue, introducing Minnesota business loans

    Business loans in Minnesota can be a game changer for your company. Whether you’re starting fresh or looking to expand, the right funding can make all the difference. From covering initial costs to boosting cash flow, these loans offer essential support. Equity financing dilutes ownership, while debt financing requires repayment but allows owners to retain control. Alternative financing options include loans for newer businesses with modest capital requirements, typically under $50,000, providing a practical solution for startups and small-scale operations.

    Understanding your options is vital as you want to choose a funding program that is conducive to your cash flow and covers your needs. This guide explores Minnesota business loans, including your available options, the pros and cons, and the application process. Specifically, we’ll answer these questions:

    A few ways to use your funds:

    Cash register outline icon
    Purchase New Equipment
    Paint roller icon
    Updates & Renovation
    Add map location icon
    New Location/ Expansion
    Upward trend line icon
    Busy & Slow Season
    Google logo

    I had an awesome representative Sean Hutchinson was very helpful, he was knowledgeable and I appreciate the way that he assisted me, he was not pushy nor did he hurry me along when we spoke. He was very attentive and helpful, he made sure to keep me updated every step of the way with the process. Thank you ♥️
    Antonia B.

    Free Consultation No Obligation

    What types of Business Loans are available in Minnesota?

    Minnesotans can access various business loan program options to fund their operations.
    Small Business Loans

    Working Capital Loans: Working capital loans in Minnesota provide financing to cover a business’s day-to-day operational expenses. Typical uses of working capital loan funds include inventory purchases, payroll, rent, and other short-term financial needs. They provide the cash flow to keep operations running smoothly and seize economic opportunities. Working capital loans are typically easier to qualify for than other business loans, making them a popular choice for small businesses needing quick funding.

    Business Line of Credit: A business line of credit in Minnesota is a flexible financing option that allows small businesses to access funds as needed. Instead of a lump sum payment, funds for a business line of credit are activated as an available credit limit. A revolving line of credit works similarly to a credit card, where you can borrow and repay funds as needed and only pay interest on the amount you use. This type of financing is ideal for covering short-term expenses, managing cash flow fluctuations, or seizing growth opportunities without applying for a new loan each time. Lines of credit provide flexible access to funds, only accruing interest on the amount drawn.

    Revenue-Based Financing: Revenue-based financing in Minnesota is a form of alternative small business funding where the company’s revenue determines eligibility and amounts. Repayment comes directly from a percentage of future revenue. This type of financing allows businesses to access capital without taking on additional debt, making it an attractive option for companies with fluctuating revenue streams.

    SBA Loans: SBA loans provide funding to help businesses start, grow, and succeed. The Small Business Administration (SBA) partially guarantees these loans, providing security for lenders and allowing small businesses better access to capital. SBA evaluates each loan application based on eligibility, which varies by industry and SBA program. These partially guaranteed loans offer favorable terms such as lower interest rates and longer repayment periods than traditional bank loans, making them an attractive option for an MN small business owner. SBA loans often provide lower monthly payments by offering longer loan terms. An SBA loan in Minnesota can be used for various purposes, including working capital and equipment purchases.

    The SBA 7(a) loan is versatile, covering several financing needs, including working capital and debt refinance. SBA 504 loan programs fund commercial real estate and other major fixed assets. Certified Development Company Loans or the 504 Loan Program are specifically designed for substantial investments like purchasing real estate or major equipment. The SBA 7(a) program offers terms up to 10 years, and if combined with real estate, may be up to 25 years. The maximum SBA 504 loan amount is $5.5 million. The SBA Microloan program also provides loans up to $50,000, making it a suitable option for smaller financing needs. Small Business Administration (SBA) financing programs include options like microloans tailored for startups, offering accessible funding for new ventures.

    Invoice Factoring: Invoice factoring in Minnesota is an alternative business funding option in which a business sells its accounts receivable to a third party at a discount. This provides immediate cash flow, allowing the business to cover expenses or invest in growth without waiting for customers to pay their invoices. The factoring company then collects the total amount from the customers directly.

    Merchant Cash Advance: A merchant cash advance (MCA) in Minnesota is a form of financing where a business receives a lump sum of money upfront in exchange for a percentage of future credit card sales. Small businesses with fluctuating revenue streams or those needing quick access to capital typically use this type of funding. While merchant cash advances can provide fast funding, they often come with high fees and may not be suitable for all businesses. Alternative funding options include private lenders, which may offer more flexible lending terms, albeit usually at higher costs.

    Business Term Loan: Business term loans in Minnesota are a type of financing in which a business borrows a lump sum and repays it with interest over a set period, with fixed interest rates and consistent monthly loan payments. These loans are typically long-term financing, but there are also short-term business loans. Businesses usually use term loan proceeds for significant investments like equipment purchases, paying off existing business debt, commercial real estate, or business expansion projects. The interest rates and terms of business term loans can vary depending on the lender and the borrower’s creditworthiness. Term loans offer a lump sum of cash upfront with a fixed repayment schedule.

    Equipment Financing: Equipment financing in Minnesota is a type of small business loan specifically used to purchase equipment and machinery for operations. Equipment loans allow businesses to acquire necessary assets without draining their cash reserves. Typically, the financed equipment serves as collateral for the loan, making it easier for companies to secure funding.

    Asset-Based Loans: Asset-based loans (ABL) in Minnesota allow small businesses to unlock the value of the assets on their balance sheet to secure funding. ABL lenders have business assets appraised and then issue loan amounts based on the appraisal value. The assets become collateral for the loan, meaning the lender can claim the assets in case of default. Some examples of asset-based business loans include commercial real estate loans, certain construction loans, secured term loans, and accounts receivable financing.
    Specialized Minnesota Business Financing Options

    The Minnesota Department of Employment and Economic Development (DEED) administers six critical programs under the State Small Business Credit Initiative (SSBCI). Each program targets different aspects of business financing. Community development efforts, like the Child Care Economic Development Funding Map, support growth across various sectors, ensuring that resources are allocated to areas with the greatest need.


    Minnesota’s DEED and the Small Business Administration offer various financial assistance programs to support small businesses. These programs provide loans and guarantees to facilitate access to funding for eligible businesses. Specialized lenders, such as certified development companies (CDCs), focus on economic development and job creation.

    Certain small business loan programs for minorities in Minnesota provide financial support and technical assistance. This helps bridge the gap in traditional financing options and emphasizes the importance of support services in securing capital.

    • Minnesota Loan Guarantee Program: This program helps lenders by guaranteeing loans for small businesses. It reduces risk and encourages lending. The program provides lenders guarantees of up to 80% of the principal on loans made to eligible businesses.
    • Growth Loan Fund: Direct loans up to $400,000 for businesses with accredited investor support that intend to complete an equity raise in the next 12 months.
    • Direct Investment Venture Capital: This option allows businesses to receive direct investments from the state. It helps startups with funding in exchange for equity.
    • Multi-Fund Venture Capital: Invests in venture capital funds that will invest in innovative Minnesota-based businesses.
    • Small Business Loan Participation Program: This program works with lenders to offer loans to small businesses. It shares the risk between the lender and DEED.
    • Automation Loan Participation Program: This program assists businesses in upgrading their technology. It provides loans for purchasing equipment that increases efficiency.

    Environmental Improvement Loans


    The Minnesota Pollution Control Agency offers small business environmental improvement loans. These loans help businesses make eco-friendly upgrades. They can cover costs like energy-efficient equipment or waste reduction systems. This program supports sustainability while helping businesses save money.

    Expanding Opportunity Fund Program

    The Minnesota Expanding Opportunity Fund Program lends to nonprofit corporations, Tribal economic development entities and community development financial institutions so they can make more loans to Minnesota small businesses.

    Emerging Entrepreneur Loan Program

    The Emerging Entrepreneur Loan Program funds certified nonprofit lenders, which make term loans to Minnesota businesses majority-owned and operated by minorities, low-income persons, women, veterans or persons with disabilities. DEED’s share runs from $5,000 to $150,000. The rate can’t exceed Wall Street prime plus 2%, with a 10% maximum. Businesses apply through a certified lender.

    The program aims to stimulate economic growth and create job opportunities in Minnesota by supporting these emerging entrepreneurs. Each nonprofit lender sets the specific interest rate, collateral requirements and other terms of its loans.

    Certified development company loans are part of the Small Business Administration’s financial assistance programs, funding significant assets like real estate and equipment. These loans help businesses maintain control and manage cash flow effectively. A 504 loan offers financing through a Certified Development Company and requires a 10% injection from the borrower. SBA’s four basic loan programs include Guaranteed Loans, Certified Development Company Loans, Small Business Investment Companies, and Microloans. The SBA places its primary emphasis on loan consideration based on the demonstrated ability of the business to repay all business-related debt, including the new loan obligation. The Small Business Administration has financial assistance programs that provide access to debt and equity, primarily from banks or other private sources.

    Direct loans are a government-backed financing option in Minnesota, offering competitive interest rates and favorable terms to support small business growth. These loans are tailored for businesses looking to expand or meet specific financial needs.

    Business Funding Options Compared

    FUNDING TYPESMAX AMOUNTSSTARTING COSTSSPEED
    Merchant Cash Advances$5k – $5mStarting at 1-6% p/mo 1-2 business days
    SBA Loan7(a) up to $5M, 504 up to $5.5MPrime + 2% to 6.5%
    4 to 12 weeks
    Business Term Loan$5k - $10mStarting at 1-4% p/mo1-3 business days
    Business Line of Credit$1k - $1mStarting at 1% p/mo1-3 business days
    Receivables/Invoice Financing$10k - $25mStarting at 1% p/mo1-2 weeks
    Equipment FinancingUp to $10m per pieceStarting at Prime Rate + 3.5%As fast as 1-2 days
    Revenue Based Financing$10K – $5mStarting at 1-6% p/mo1-2 business days

    What types of industries are most prominent in Minnesota?

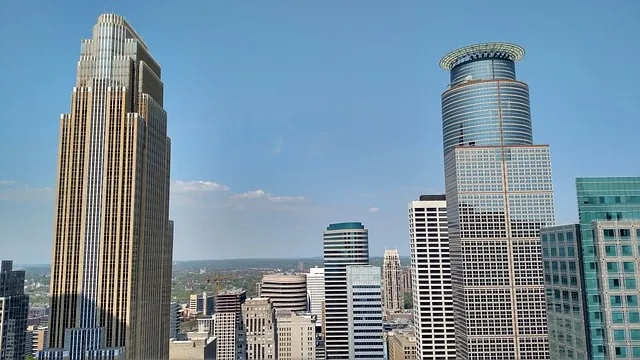
    Downtown Minneapolis skyscrapers under a clear blue sky, illustrating the industries most prominent in Minnesota

    Minnesota has a diverse economy and a strong focus on small businesses, which create jobs and support local communities. They contribute significantly to the state’s economy. In fact, small businesses make up about 99% of all companies in Minnesota. This shows how important they are for growth and stability. As a result, the state has a high median household income.

    While many industries thrive in Minnesota, here are some of the state’s most prominent sectors:

    United Capital Source logo on a professional background.

    Healthcare

    Minnesota is home to many healthcare providers. The Mayo Clinic, located in Rochester, is one of the best hospitals in the world. Healthcare accounts for many jobs in the state, and many small businesses support this industry.

    Sheet metal roll icon for metal manufacturing

    Manufacturing

    Manufacturing is another major industry. It includes companies that produce machinery, electronics, and food products. Minnesota ranks among the top states for manufacturing output. Small manufacturers help drive innovation and create jobs.

    Leaf icon for beauty salons and spas

    Agriculture

    Agriculture has been vital to Minnesota’s economy for years. The state produces corn, soybeans, and dairy products. Many small farms operate alongside larger agricultural businesses. They contribute to local food systems and sustainability.

    United Capital Source logo on a professional background.

    Retail Trade

    Minnesota has significant retail trade, including stores, restaurants, and online businesses. The state features the nation’s largest mall in Bloomington, the Mall of America. Local shops provide unique products and services that attract customers, and small retailers often build strong relationships with their communities.

    Logo of United Capital Source, a leading financial services provider.

    Finance and Insurance

    The finance and insurance sector is a cornerstone of Minnesota’s economy. Small financial firms offer clients personalized services, enhancing market competition.

    Technology

    Technology is rapidly growing in Minnesota. The state has a vibrant tech scene with many startups and established firms. Companies focus on software development, cybersecurity, and biotechnology, and small tech businesses contribute fresh ideas and innovations.

    What are the advantages of Minnesota Business Loans?

    Small business loans in Minnesota offer several advantages to entrepreneurs looking to grow their businesses. These loans provide access to capital for business expansion, purchasing equipment, hiring employees, or even covering unexpected expenses.

    By obtaining a business loan, entrepreneurs can take advantage of growth opportunities that may not have been possible otherwise. Additionally, these loans can help improve cash flow management by providing strategic funds. Utilizing loan funds for targeted projects like marketing can increase market presence and profit margins.

    Small business loans in Minnesota also come with competitive interest rates and flexible repayment terms, making them an attractive option for business owners. Furthermore, by establishing a positive credit history through timely loan repayments, entrepreneurs can improve their chances of securing future financing at favorable terms.

    What are the disadvantages of Minnesota Business Loans?

    Small business loans in Minnesota come with several disadvantages that entrepreneurs must consider before taking on debt. One drawback is the potential for high interest rates, which can significantly increase the overall cost of borrowing.

    Additionally, some lenders may require personal guarantees or collateral, putting the borrower’s personal assets or business assets at risk if the business fails to repay the loan. Another disadvantage is the strict eligibility criteria that small businesses must meet to qualify for a loan, making it challenging for newer or less established businesses to access funding.

    Furthermore, some business loan repayment terms can be inflexible, leading to financial strain if the business experiences fluctuations in cash flow. While small business loans can provide much-needed capital, entrepreneurs must carefully weigh the drawbacks before borrowing.

    PROS
    Circle checkmark icon
    Access to capital for business expansion.
    Circle checkmark icon
    Competitive interest rates and flexible repayment terms.
    Circle checkmark icon
    Improved cash flow management.
    Circle checkmark icon
    Positive credit history for future financing opportunities.
    CONS
    Close
    High interest rates.
    Close
    Personal guarantees or collateral may be required.
    Close
    Strict eligibility criteria.
    Close
    Inflexible repayment terms for some business loans.

    How to apply for a Business Loan in Minnesota:

    The application’s required paperwork depends on your chosen Minnesota business loan. How quickly funds arrive depends on the product, from about 24 hours to several weeks for SBA loans.

    Who qualifies for a business loan in Minnesota?

    Requirements vary by product and lender. As a starting point, UCS works with Minnesota businesses that have at least 6 months in business, at least $12,000 in monthly revenue, and a personal credit score of 475 or higher. Stronger credit, more time in business and higher revenue usually open more options, such as SBA and term loans. If your business is under 6 months old, the SBA microloan program and your local Small Business Development Center are good places to start.

    Here’s how to apply:

    Step 1: Choose the Right Product

    The first step is choosing the most sensible solution to the problem at hand. This should require a decent amount of research, as each product is designed for different types of expenses and cash flow cycles. Are you looking to cover a short-term or long-term cost? Is demand expected to increase or decrease in the coming months?

    Considering the funds’ purpose will also help us determine the correct borrowing and terms for your needs.

    Step 2: Gather Your Documents

    Here are the documents and information commonly requested for Minnesota business loans:

    • Driver’s license.
    • Voided business check.
    • Business bank account statements from the past three months.
    • Invoice for equipment (for Equipment Financing).
    • Credit card processing statements from the past three months (for Merchant Cash Advance).
    • Accounts Receivable Aging Report (for Accounts Receivable Factoring).
    • Accounts Receivable (for Accounts Receivable Factoring).
    • Debt Schedule (for Accounts Receivable Factoring).

    SBA Loan options require additional documents and information, such as a business plan. Preparing comprehensive documentation, including business financials and a business plan with projections, is crucial for loan applications. The Small Business Administration developed government-backed loans to support the growth of small businesses. Visit our SBA Loan page to learn what’s needed for the application.

    Step 3: Fill Out Application

    You can begin the application process by calling us or filling out our one-page online application. Either way, you’ll be asked to enter the information from the previous section along with your desired funding amount.

    Step 4: Speak to a Representative

    Once you apply, a representative will contact you to explain the repayment structure, rates, and terms of your available options. This way, you won’t have to worry about any surprises or hidden fees during repayment.

    Step 5: Receive Approval

    If and when you’re approved, funds for Business Term Loans, Business Lines of Credit, Working Capital Loans, Equipment Financing, Merchant Cash Advance, Revenue-Based Business Loans, and Accounts Receivable Factoring should then appear in your business bank account in anywhere from 24 hours to two weeks, depending on the product. For SBA Loans, it usually takes 4 to 12 weeks (or more in some cases) to receive funding.

    Your Business Financing Gets Set Up – Now What?

    Your Minnesota business loan isn’t just a way to get financing for your business. It’s also an excellent opportunity to start building (or improving) your credit.

    Regardless of the type of business loan you get, make all your required payments on time and in full. If you get a business credit line or another form of revolving credit, keep your balance below the credit limit. Establishing a business credit history begins with differentiating personal and business finances by obtaining an EIN. Improving a business credit score includes making timely payments and maintaining a low credit utilization ratio.

    Consistently making your business financing payments on time and in full will positively impact your credit. And that means preferred rates and terms when you next need business financing.

    What if I'm declined for a Business Loan in Minnesota?

    If your application is declined, you might have applied for the wrong product for your cash flow. We would likely recommend a different product with a more manageable repayment structure in this case.

    Your application might also be declined after determining that you cannot afford to take on more debt. Instead, your needs and financial circumstances might be better suited for another financing tool, like a business credit card or personal loan. Both options are usually easier to qualify for than business loans.

    If your credit score is preventing you from accessing financing, check your credit reports for errors and work on the issues keeping your score down before you reapply. Monitoring loan amortization schedules helps businesses effectively plan for their periodic payments.

    We have access to various business funding options in Minnesota.

    Proven to work for our clients. Get one today.
    Free Consultation No Obligation

    Minnesota Business FAQs

    What lenders offer Business Loans in Minnesota?

    Minnesota business owners have various financing options, including private lenders, nonprofits, and government loans. Choosing the best lender depends on your needs and qualifications.

    Traditional Lenders

    Banks and credit unions play a significant role in the small business loan sector. They usually have lower interest rates than other lenders, but strict qualifications can make it challenging to get approved. Most traditional bank loans require excellent credit, high revenue, and collateral. In addition, the application process can be lengthy. Borrowers must submit extensive documentation, including financial statements and tax returns.

    National banks differ from local banks and credit unions. National banks often have more resources but may lack personal service. Local banks and credit unions tend to know their communities better. They may offer more flexible terms for borrowers.

    Alternative Lenders

    Alternative lenders have changed the landscape of small business financing. Online lenders often provide quicker decisions and faster funding. Their qualifications are less stringent than traditional lenders, making them accessible to many business owners. However, they may charge higher interest rates as a tradeoff for speed and accessibility.

    Many businesses find alternative lenders appealing when facing urgent cash flow needs. The ease of applying online saves time for busy entrepreneurs.

    Small Business Loan Marketplaces

    Small business loan marketplaces (like UCS) are game changers for Minnesota small businesses. These platforms allow owners to apply to multiple lenders using a single application, reducing time and stress during the borrowing process.

    Borrowers often receive several funding offers from which to choose. This empowers them to select the best option for their needs and cash flow situation. Some marketplaces even connect applicants with business loan experts who guide borrowers through the process, helping them make informed decisions.

    Community Development Financial Institutions (CDFIs)

    Community Development Financial Institutions (CDFIs) also support Minnesota businesses. CDFIs focus on underserved communities and offer tailored loan products. They aim to help businesses that might struggle with traditional loans. Local banks, credit unions, and dedicated lender organizations comprise Minnesota’s lending ecosystem, providing a range of options for small business financing.

    These institutions often provide lower interest rates and flexible terms. They understand the unique challenges faced by small businesses in certain areas. CDFIs play an essential role in promoting economic growth within local communities.

    Are there government assistance programs for Minnesota Small Businesses?

    Government assistance plays a crucial role in supporting small businesses in Minnesota. Many programs exist to help business owners access funding and resources. These programs aim to boost local economies and encourage entrepreneurship. The Reservist and Veteran Business Loan Program assists military reservists and veterans starting or expanding a business in Minnesota.

    DEED Support

    The Minnesota Department of Employment and Economic Development (DEED) offers various resources. DEED provides financial assistance through grants and loans. They focus on helping small businesses grow and create jobs. The department also provides training programs to help entrepreneurs improve their skills. Additionally, the Minnesota Chamber of Commerce offers resources that support long-term financing for business expansion.

    Minnesota Chamber of Commerce

    The Minnesota Chamber of Commerce also provides valuable assistance. They offer support through networking events and educational workshops. These events help business owners learn about best practices.

    Chamber members can access exclusive resources, including information on state laws and regulations affecting small businesses. The Chamber advocates for policies that benefit the business community.

    SCORE Minnesota

    SCORE Minnesota is another crucial player in supporting small businesses. This organization offers free mentoring services, and experienced professionals guide entrepreneurs through the challenges they face.

    SCORE hosts workshops on various topics, such as marketing and finance. These workshops provide essential knowledge for business growth, and entrepreneurs can gain insights from mentors’ real-life experiences.

    SBA District Office

    Minnesota’s Small Business Administration (SBA) District Office offers numerous resources. The SBA provides information on loan programs, including SBA Express Programs, which allow quick access to funds for eligible businesses. The Minnesota District Office provides guidance and support tailored to the local business ecosystem.

    The SBA also connects business owners with local lenders. They help entrepreneurs understand the application process for loans. Business owners can find guidance tailored to their unique needs.

    Local Government Assistance

    Local governments in Minnesota also offer assistance. Many cities have economic development offices that support small businesses. These offices provide information on grants, tax incentives, and other resources.

    Local governments often host events to connect business owners with funding sources. They also work closely with organizations like DEED and the SBA to ensure comprehensive support for small businesses.

    What Minnesota Business Grants are available?

    Minnesota offers several business grants to support local entrepreneurs. These grants help businesses access funds for growth and development. Here is a list of small business grants available in Minnesota.

    • Minnesota Department of Employment and Economic Development (DEED) Grants: DEED provides various grants to support small businesses. Its programs focus on job creation and economic growth. DEED often funds projects that improve infrastructure or expand operations.
    • Small Business Innovation Research (SBIR) Grants: This federal program offers funding for research and development. It helps small businesses create innovative products and services. Companies can receive significant amounts of money to develop their ideas.
    • Rural Business Development Grants: The USDA offers these grants specifically for rural areas. They aim to strengthen the economy in less populated regions. Eligible projects can include business planning, training, and operational costs.
    • City-Specific Grant Programs: Many cities in Minnesota have their own grant programs. For example, Minneapolis’s Great Streets program supports local businesses with improvement funding. Each city may have different eligibility requirements.
    • Community Development Block Grant (CDBG): This federal program supports community development projects. Local governments can use these funds to assist businesses in need. The goal is to create jobs and improve the local economy.
    • Business Start-Up Grants from Nonprofits: Some nonprofit organizations offer grants for new businesses. These organizations often focus on underserved communities or specific industries. They provide financial assistance alongside mentorship and resources.
    • The Minnesota Department of Agriculture (MDA) Grants: MDA offers grants specifically for agricultural businesses. These grants support sustainability, innovation, and market expansion efforts within the agriculture sector.

    What tax credits are available for Minnesota Businesses?

    Minnesota offers various tax credits to support small businesses. These credits help reduce costs and encourage growth. They can improve cash flow and make it easier to invest in the business. Here is a list of some key tax credits available for small businesses in Minnesota:

    • Research and Development Tax Credit: This credit supports companies that invest in research and development. It provides a percentage of qualifying R&D expenses, which can significantly lower tax bills.
    • Job Creation Fund: This program is a grant, not a tax credit. DEED provides up to $1 million to approved businesses after job creation and capital investment goals are met. At minimum, a business must invest $500,000 in real property improvements and create 10 new full-time equivalent jobs ($250,000 and 5 jobs for targeted populations).
    • Work Opportunity Tax Credit: According to the IRS, this federal credit is available for wages paid to certain individuals who begin work on or before December 31, 2025. Check the IRS for any extension.
    • Historic Structure Rehabilitation Tax Credit: This credit supports the restoration of historic properties. Businesses can receive a percentage of rehabilitation costs as a tax credit.

    Can I get a Minnesota Business Loan with Bad Credit?

    A low credit score limits financing options, but credit-challenged Minnesota small business owners can still access needed capital with bad credit business loans. These specialized financing options focus on a business’s cash flow and growth potential more than the personal credit score of the business owner(s), increasing your chances of credit approval.

    Several alternative lenders specialize in providing business financing for credit-challenged entrepreneurs. Online lenders offer easy online applications with minimal documentation, quick decisions, and fast funding, which benefits small businesses with urgent capital needs.

    However, business loans for bad credit often carry high interest rates and increased fees. In addition, you may receive a lower maximum loan amount, have shorter repayment terms, and require more frequent repayment. These conditions can lead to further financial strain if not properly managed. Ensure you have a plan and budget before agreeing to a bad credit business loan.

    A popular strategy for MN business owners is to use a bad credit business loan as short-term financing until their credit improves. With a better credit score, entrepreneurs can potentially access lower-cost, long-term loans and pay off bad credit business loan debt.

    Business Loans in Minnesota - Final Remarks

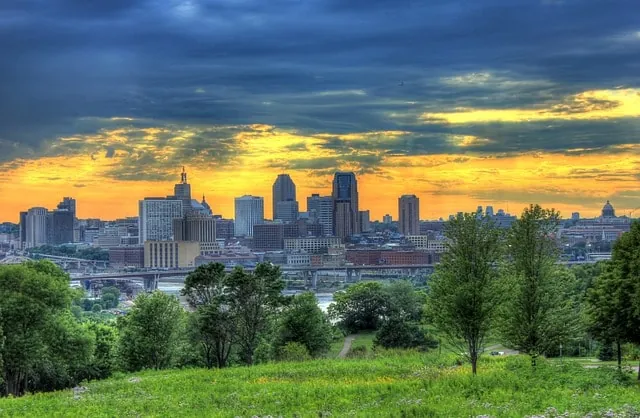
    St. Paul skyline under a dramatic orange sunset seen from a green hilltop park, closing remarks on Minnesota business loans

    Navigating business loans in Minnesota can be a game-changer for your venture. You have various options tailored to your needs, from specialized financing to government programs.

    Understanding the advantages and potential drawbacks is essential for making informed choices. Explore available loans, grants, and support tailored for Minnesota businesses.

    Contact us if you’re ready to start your Minnesota business loan journey. Our alternative financing experts can help you find the most advantageous business loans to fuel growth in the North Star State.
    Written by
    Picture of Jared Weitz

    Jared Weitz

    Jared Weitz is the Founder & CEO of United Capital Source (UCS), one of the nation’s fastest-growing business financing marketplaces. Since founding the company in 2011, Jared has built a technology-enabled platform that has facilitated over $1.6 billion in funding to more than 40,000 businesses across the United States. Under his leadership, UCS has evolved into a full-service marketplace that connects business owners with 80+ lenders while providing hands-on guidance throughout the entire funding process. UCS works directly with each applicant—leveraging technology and experienced funding professionals to match businesses with the right financing options, structure deals, and guide them from application through funding and future growth. Jared’s work has earned national recognition, including the National Commercial Loan Broker of the Year award in 2019, and placements on the Inc. 5000 list in 2015 and 2017. He also serves as Broker Council Co-Chairman for the Small Business Finance Association, where he helps advocate for expanded access to capital for small businesses nationwide.

    Google logo

    I give this company a 10 star if I could very good company especially when you starting your business. This company worked with my credit. Matthew was fantastic he walked us through step by step to get our business financed.
    Steven D.

    Free Consultation No Obligation

    Why Choose United Capital Source?

    Why businesses choose UCS:

    1
    See your options with a soft credit check that won’t affect your score
    2
    Access to 80+ lenders with multiple products to choose from
    3
    Financing up to $25 million, up to $5 million in as few as 3 days
    4
    4.9-star rating from 1,600+ happy clients!

    Ready to grow your business? See how much you qualify for:

      Current monthly sales deposit average to your business bank account?

      How much Working Capital would you like for your business?

      By providing your phone number and submitting this form, you consent to receive text messages from United Capital Source about your financing inquiry. Message frequency may vary. Message and Data Rates may apply. Reply STOP to opt out of further messaging and HELP for assistance or call 646-448-1700. View our Privacy Policy and Terms.

      AL AK AZ AR CA CO CT DE FL GA HI ID IL IN IA KS KY LA ME MD MA MI MN MS MO MT NE NV NH NJ NM NY NC ND OH OK OR PA RI SC SD TN TX UT VT VA WA WV WI WY DC
      Need Instant Help?
      Call Us Now At:

        Current monthly sales deposit average to your business bank account?

        How much Working Capital would you like for your business?

        By providing your phone number and submitting this form, you consent to receive text messages from United Capital Source about your financing inquiry. Message frequency may vary. Message and Data Rates may apply. Reply STOP to opt out of further messaging and HELP for assistance or call 646-448-1700. View our Privacy Policy and Terms.

        At UCS, we understand the value of your time and want to ensure that your application has a great chance of approval. Please take note of the following details before applying:
        • To be eligible, it’s necessary to have a business bank account with a well-established U.S. bank such as Chase, Wells Fargo, Bank of America, Citibank, or other major banks. Unfortunately, online-based bank accounts like PayPal, Chime, CashApp, etc., are not permitted.
        • When describing your current average monthly sales deposits to your business bank account, please provide accurate information. Our approval process is based on your current business performance, and it’s essential to provide accurate details about your current sales in the first question on the application form. We cannot approve applications based on projected revenues after receiving funding.
        We appreciate your understanding and cooperation in ensuring a smooth and successful application process.
        Rated 4.9 out of 5
        |
        4.9 from 1,600+ reviews
        Rated 4.9 out of 5
        4.9 from 1,600+ reviews

        Take a minute, Get a FREE Consultation