A business car lease is a fixed-term agreement to use a vehicle without owning it. Payments cover expected depreciation plus a financing charge; the company returns or buys the car at the end of the term, with mileage limits and condition standards set up front.
A fast-funding small business loan is financing that can be approved and deposited in 1 to 3 business days, usually through an online lender or an alternative financing provider. Speed depends on how quickly your bank statements are verified and how clean your documentation looks. Most delays come from missing paperwork or identity mismatches, not from lenders moving slowly.
A working capital loan is business financing used to cover day-to-day operating expenses—such as payroll, rent, inventory, and vendor bills—rather than long-term assets like real estate. You receive a lump sum and repay it over a fixed term, usually with daily, weekly, or monthly payments. This is different from a business line of credit, which provides a revolving spending limit
Quick MCA Requirements for 600 Credit Score (One-Screen Summary) Bank denial is common. Banks underwrite based on fixed-payment affordability and often require higher credit scores, collateral, and tax returns. MCAs are primarily revenue-based. If your credit score is around 600 and your deposits are steady, your bank statements—not your FICO—usually determine whether you’re approved for an MCA and what it
Same-week MCA funding is usually a documentation and verification issue, not a credit-score issue. Your deposits and trends matter more than your FICO. Understanding the difference between approval, contract signing, and funding disbursement is critical.
Approval means an underwriter reviewed your statements and offered terms. Contract signing means you agreed to the factor rate, holdback, and total payback. Funding
For many small businesses, the key to growth and stability is signing that one game-changing deal with a substantial client. They have to know where to look for the most lucrative opportunities. Unfortunately, business owners tend to disregard a considerable source of revenue for smaller businesses altogether. Believe it or not, the United States federal government must routinely purchase goods
The biggest misconception many small business owners have about business credit is that they have a business credit profile. What’s more, of those business owners aware and mindful of their business credit, many of them have likely never heard of the FICO SBSS Score or FICO Small Business Scoring Service.
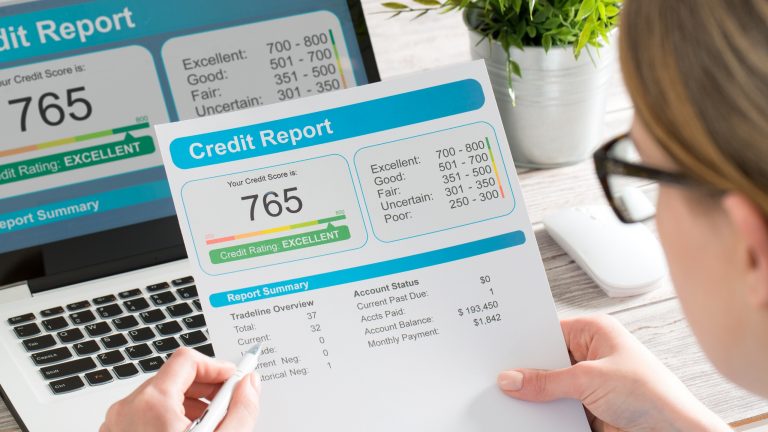
As if protecting personal credit wasn’t stressful enough, business leaders have another credit score to worry about. It’s called your business credit score, and it has a significant effect on your capacity to grow. Without strong business credit, beneficial business partnerships and financial resources are much harder to obtain. Though business and personal credit have several commonalities, establishing and maintaining
The net working capital formula allows you to see exactly how much cash you can spend at this time, along with whether or not your business has enough assets to cover short-term expenses. This equation requires just two numbers: your business’s current assets and your business’s current liabilities.
At first, seasonality seems more like a weakness than a strength in the business world. However, virtually all businesses experience some degree of seasonality. What business doesn’t have customers whose behavior is influenced by the weather? For certain industries, that influence is just a little more extreme.